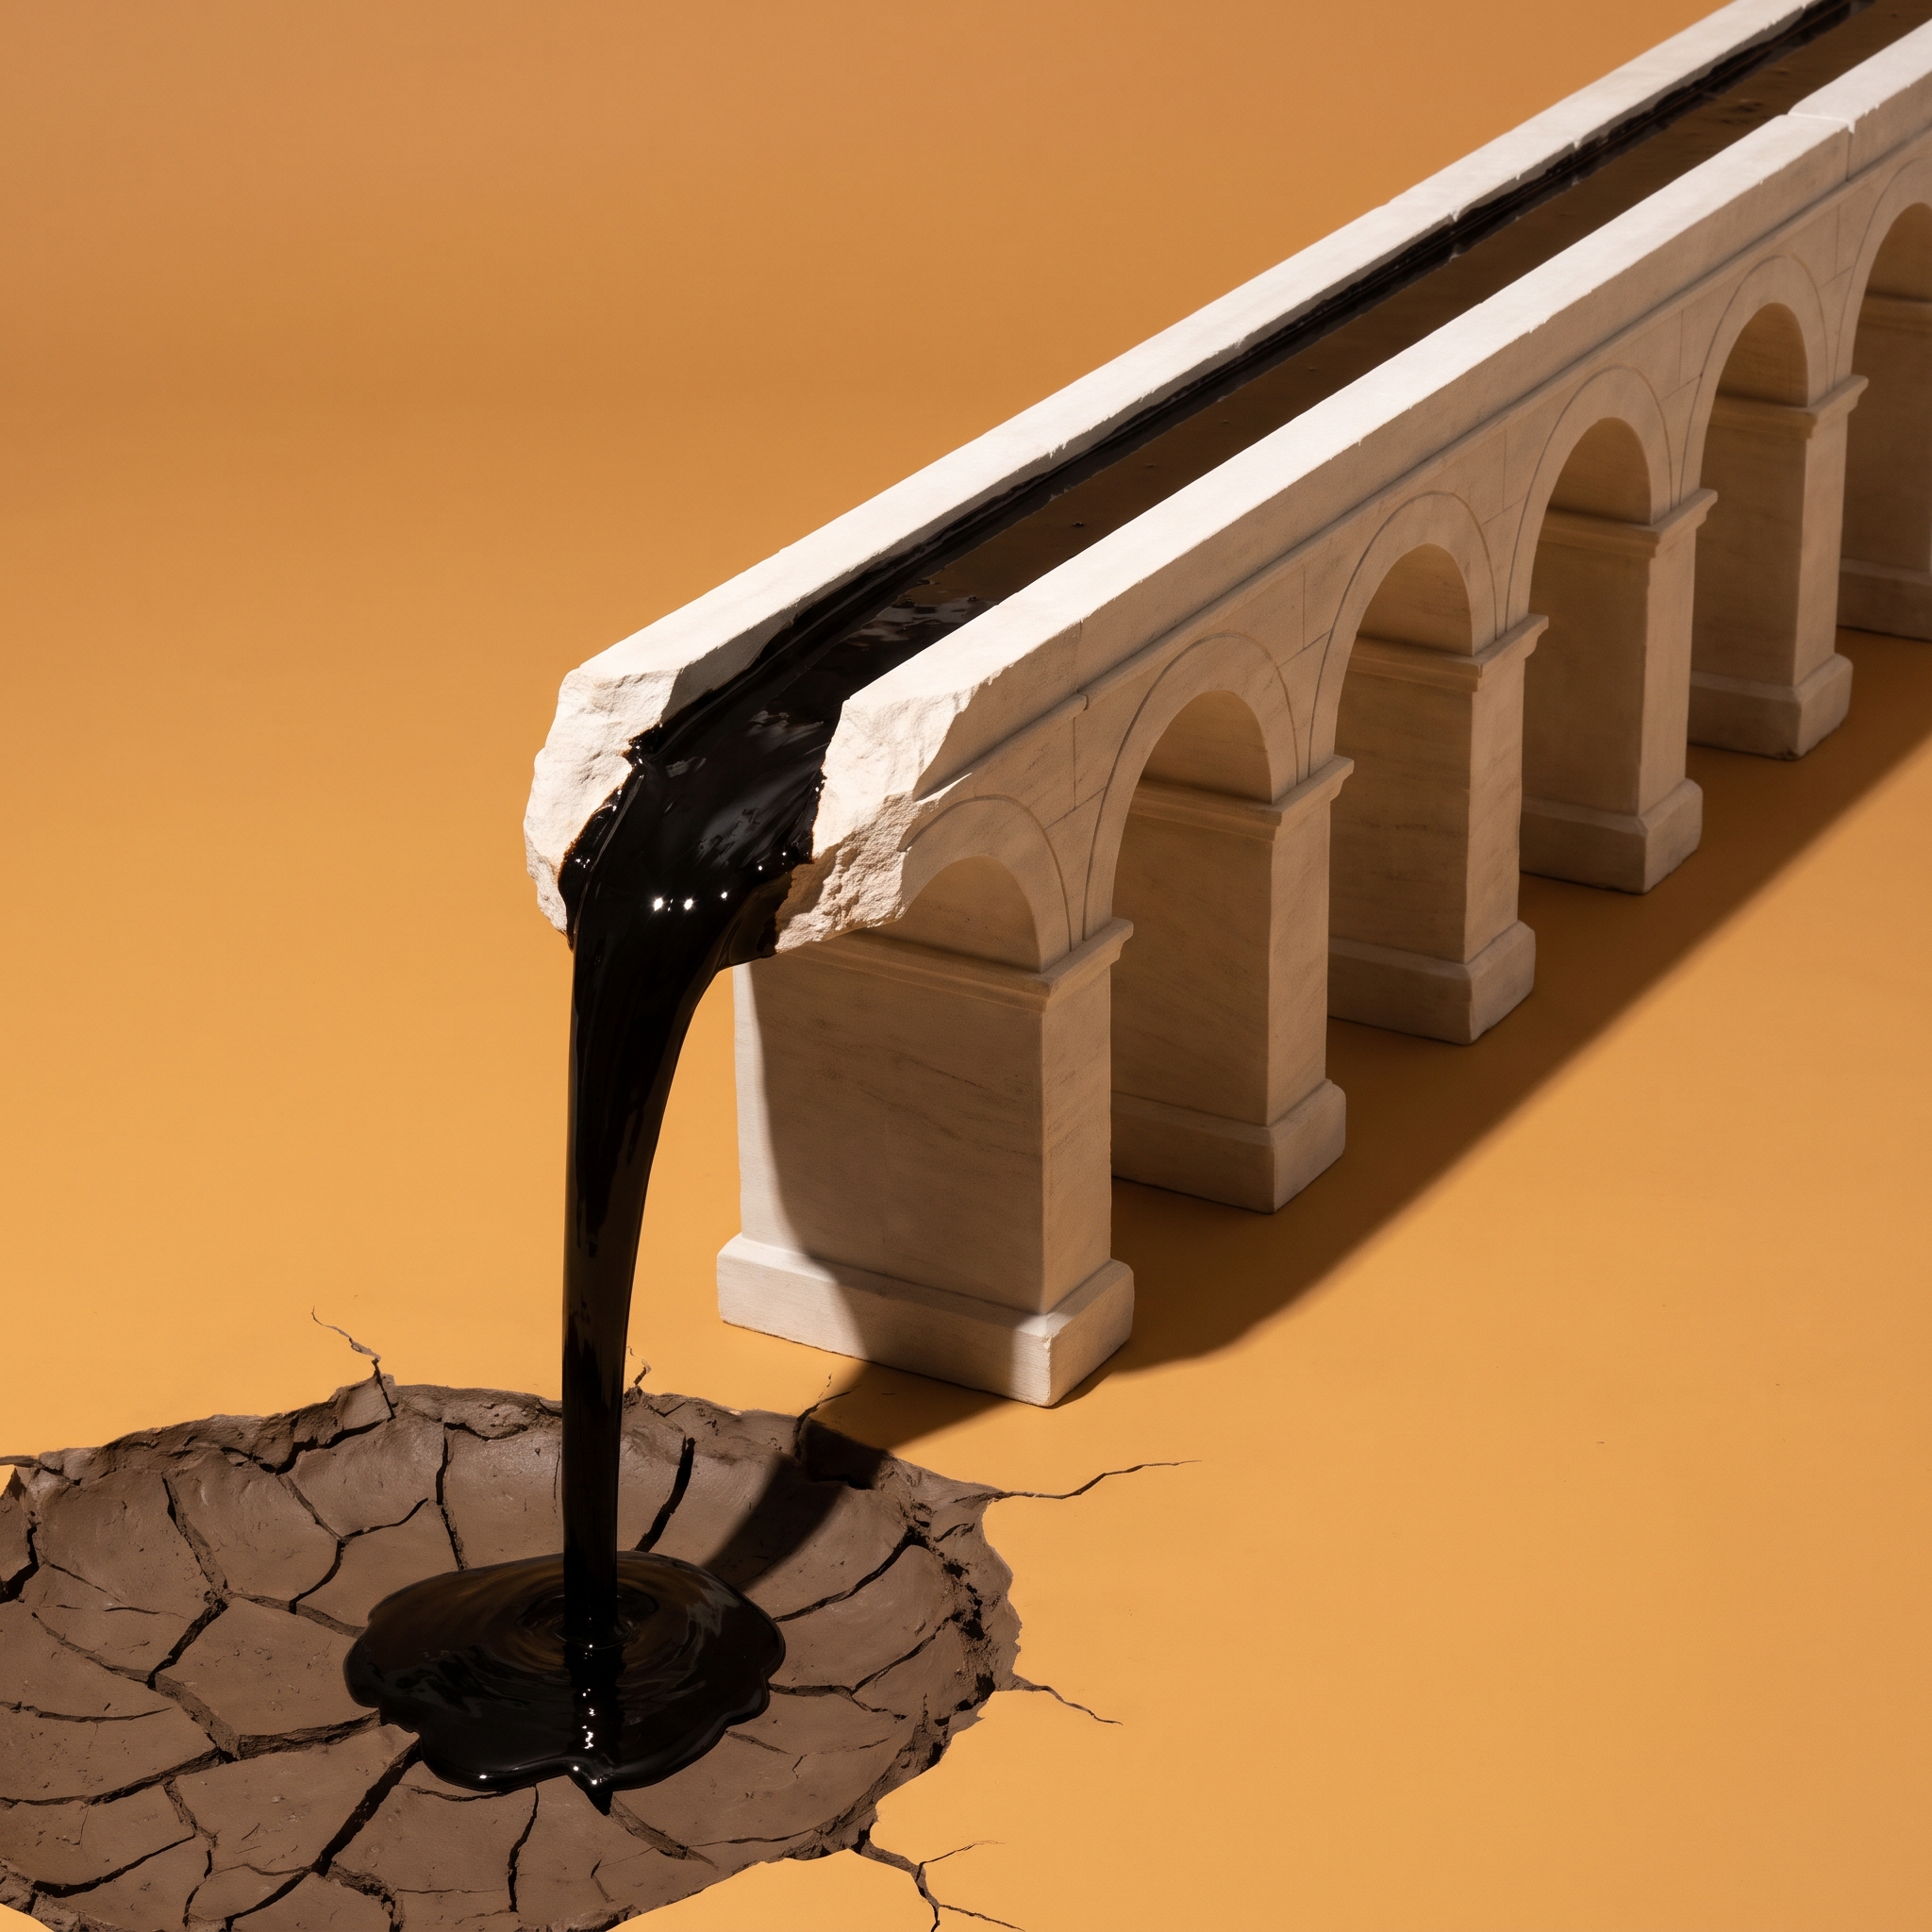
Marcus Vale: Before we get started — can I just say, I read the Zambia numbers last night and I'm still a little annoyed they aren't more famous.
Ben Okonkwo: Hm, in what sense annoyed?
Marcus Vale: The comparison is almost too clean. Botswana, Zambia, same independence moment, same resource windfall roughly, and then one of them grows faster than almost any other country on earth for thirty-five straight years and the other becomes the textbook case for everything going wrong. And nobody outside development economics is talking about the contrast.
Ben Okonkwo: Right — and that controlled quality is actually why researchers keep returning to it. It's not just a cautionary tale about Zambia. The pairing isolates governance as the variable because you can't blame the resource. Both countries had the resource.
Marcus Vale: So today — the resource curse. Why mineral wealth produces the opposite of what it should, and whether that outcome is baked in or conditional.
Ben Okonkwo: And I want to start with the intuition, because I think the jargon — resource curse, rentier state — it kind of slides off people. So let me try a plain version. Imagine you get handed a trust fund the day you graduate. You never have to get a job. And the issue isn't just that you might spend it carelessly — it's that you never go through the thing that forces you to build skills. The negotiation, the accountability to an employer, the dependency that makes you actually listen to someone else. A government that funds itself from resource rents instead of taxing its population skips that entire developmental stage. It never builds the institutions that taxation would have forced it to build.
Marcus Vale: And Botswana grew faster than almost any other country for thirty-five years despite being one of the world's largest diamond producers. That's the fact that breaks the simple version of the story.
Ben Okonkwo: It does — and that's exactly the tension. Because if diamonds automatically curse you, Botswana shouldn't exist as a data point. But it does. And Zambia's copper tells the other story just as clearly. So what actually made the difference?
Marcus Vale: What did those two civil servants in 1966 inherit that was different.
Ben Okonkwo: That's the question. And the answer, I think, is narrower and more uncomfortable than the standard story lets on.
Marcus Vale: Walk me through it.
Ben Okonkwo: So the uncomfortable part is the sequencing. Botswana didn't just get lucky with its leaders — it already had functioning courts and a tax apparatus before diamonds became the story. Which means when the rents arrived, they layered on top of something. They didn't replace it.
Marcus Vale: And Nigeria is the inverse. Oil arrives to a state that's still forming. The government never has to knock on a citizen's door for money — so it never builds the machinery that knocking requires.
Ben Okonkwo: Right — but what does that machinery actually look like? Like concretely.
Marcus Vale: Courts. Tax courts specifically. You need to assess someone's income, which means — wait, actually think about what that requires. You need to know they exist. You need a census. You need property records. You need enforcement. And then when you get it wrong, you need somewhere to appeal. That's fiscal capacity. It's this whole institutional stack that taxation forces you to build almost by accident.
Ben Okonkwo: And Terry Lynn Karl's 1997 work basically documents that — institutional weakness as the catalytic factor. Not the resource itself.
Marcus Vale: Right. Karl's argument is that the resource doesn't curse you. The fiscal substitution does. Nigeria today collects roughly five percent of GDP in taxes. Five. While sitting on oil worth billions. That's not a revenue problem — that's the entire accountability relationship just... absent.
Ben Okonkwo: Five percent — and Botswana is what, in comparison?
Marcus Vale: One of the highest tax-to-GDP ratios in Africa. And it taxes diamond revenues at between fifty and eighty percent. So Botswana is simultaneously extracting rents aggressively AND demanding money from its own population. It never let one replace the other.
Ben Okonkwo: The trap isn't having the resource. It's what having the resource lets you skip.
Marcus Vale: Exactly that. And once you've skipped it — here's the deal — you've also skipped the political pressure that comes with it. Because when a government taxes you, it has to answer to you eventually. You complain. You organize. The taxation-accountability link is almost mechanical. It's not idealism. It's structural.
Ben Okonkwo: Hm. So the rentier state isn't just a fiscal description — it's describing a broken feedback loop.
Marcus Vale: Broken and self-sealing. Because weak institutions can't regulate the extraction that's replacing taxation, so the rents keep flowing, the accountability keeps not existing — it compounds. Uganda discovered oil in 2006 and by 2016 extraction revenues were already being routed into military spending and patronage. The trap set before the first barrel shipped.
Ben Okonkwo: So the question isn't whether you found oil. It's what you already were when you found it.
Marcus Vale: And that's the part that breaks the boom-time optimism. Because you'd think — okay, commodity prices spike, money floods in, surely some of it sticks in productive ways. But South Africa is sitting on the world's most valuable mineral reserves and during the 2001 and 2008 booms, while mineral-rich states globally grew around five percent per annum, South Africa's extractive industry was actually contracting. Roughly one percent per annum. Negative. During the supercycle.
Ben Okonkwo: Wait — contracting during the boom?
Marcus Vale: Contracting. The price signal was screaming and the institutional environment couldn't respond to it. That's the trap operating at the macro level.
Ben Okonkwo: And that's — okay, that's actually the mechanism made visible. Because the standard assumption is that a commodity supercycle at least generates windfall, even if the windfall gets misallocated. But South Africa couldn't even capture the upside. Which means rent-seeking had already displaced productive investment so thoroughly that a price boom couldn't reverse it.
Marcus Vale: Exactly. Political competition had shifted. You're not competing to build a mine; you're competing to capture the license to operate one someone else built. That's rent-seeking. And it's not irrational — it's the highest-return activity available in that institutional environment.
Ben Okonkwo: Mongolia is the same story on a different continent, right? Mining-dependent, same dynamics — which is what makes me think this isn't an Africa problem or a governance-culture problem. The scholarly consolidation on this spans Africa, Asia, the Pacific. The cross-regional confirmation is what turns it from a cautionary tale into a structural pattern.
Marcus Vale: Right. And Travis Gilly's comparative work on fiscal disaggregation actually points the causal arrow pretty cleanly — resource-rich autocracies as a comparison class, linking the absence of taxation to the absence of accountability. It's not correlation dressed up as mechanism. The direction is there.
Ben Okonkwo: Hm. So boom times don't save you.
Marcus Vale: The trap holds even when the commodity price is in your favor. That's the durable equilibrium part. It's not sensitive to the external price environment.
Ben Okonkwo: I want to put a face on that — because I think Mongolia in 2011 is actually the clearest version. Copper prices at a fifteen-year high, Oyu Tolgoi just coming online, projections for double-digit GDP growth. And what you actually see is factional competition over mining contracts intensifying, not investment in anything that outlasts the cycle.
Marcus Vale: That's rent-seeking in real time. Someone in Ulaanbaatar in 2011 is doing the math and the math says fight for the license, not build the refinery.
Ben Okonkwo: And weak institutions can't stop that calculation — they can't regulate extraction, they can't enforce diversification, they can't even reliably audit the royalties. So the rents compound the weakness and the weakness lets the rents flow unchecked. Now — the obvious question is whether you can design your way out. Sovereign wealth funds, diversification mandates, foreign firm frameworks. And that's actually where the picture gets worse, not better — which we should get into.
Marcus Vale: Frankly that's the part I want to stress-test. Because every proposed fix assumes the institutional strength that the trap prevented from forming. That's the chicken-and-egg and I don't think it's been solved.
Ben Okonkwo: And that circularity is what I keep getting stuck on — because the fix assumes the thing that's broken. Walk me through the sovereign wealth fund case, because Norway gets cited constantly as the model.
Marcus Vale: Norway built its fund on top of a tax state that already existed. Full stop. The institutional capacity to resist raiding the fund — audits, independent oversight, political accountability — Norway had all of that before a single krone of oil revenue went in.
Ben Okonkwo: So the fund didn't create the discipline. The discipline made the fund work.
Marcus Vale: Botswana same story. The fifty-to-eighty percent diamond tax rate — that's not a wealth fund mechanism, that's a pre-existing fiscal apparatus doing its job. And Uganda is — look, Uganda is the version that removes all ambiguity. Oil discovered 2006, and by 2016, before extraction had even fully scaled, the revenues were already routing into military budgets and patronage networks. The institutional trap closed before the first serious barrel shipped.
Ben Okonkwo: Before extraction fully began.
Marcus Vale: Before. Which means — and this is the part that breaks the design-solution optimism — you can't sequence your way out by building the fund first. The political pressure to raid it arrives faster than the institutional resistance to that pressure can be constructed.
Ben Okonkwo: Hm. So what about the foreign firm argument? The case that multinationals bring capital and technical expertise that the state couldn't generate internally — does that at least break the cycle somewhere?
Marcus Vale: It compounds it, actually. I mean — think about what foreign extraction capacity actually does to state-building incentives. If a Nigerian official can collect royalties from a Shell contract without ever building a tax authority, there's no pressure to build one. The expertise fills the void, which removes the discomfort that would have forced domestic institution-building.
Ben Okonkwo: And Nigeria specifically — the geopolitical layer makes it worse, right? It's not just legacy colonial arrangements.
Marcus Vale: US and China both now. Different entry points — China through infrastructure-for-access deals, the US through existing firm relationships — but the structural effect on Nigerian administrative capacity is the same. External actors handle the complexity, the rent flows, and the state never has to develop the bureaucratic muscle to manage its own extraction.
Ben Okonkwo: So diversification mandates — that's the last exit ramp. And I'm guessing the evidence there is also thin.
Marcus Vale: Genuinely thin. The honest finding is that diversification probably has to accompany institutional reform, not precede it — but institutional reform is exactly what rent-capture arrangements are structured to prevent. So you need both simultaneously, which is — wait, that's just restating the trap with extra steps. The chicken-and-egg doesn't resolve. It just gets dressed up as a policy roadmap.
Ben Okonkwo: And that's what makes Uganda the clearest case — not because it's the worst outcome, but because the timeline is so compressed. The trap visible in real time, before anyone could argue the extraction hadn't started yet.
Marcus Vale: And that image — Lusaka and Gaborone in 1966 — stays with me. Two civil servants, same morning, same inherited mineral wealth, and what diverged wasn't the resource. It was what was already in the room when the resource showed up.
Ben Okonkwo: Right — and Botswana proves the curse isn't destiny. That's the conditional part. But the conditionality is almost... I mean, it's uncomfortable, because what Botswana had that Zambia didn't wasn't a better policy or a wiser leader in a decisive moment. It was institutional groundwork that pre-dated the diamonds entirely. You can't go back and install that.
Marcus Vale: Basically, the countries that escaped it did so before they needed to.
Ben Okonkwo: That's — yeah. That's the most honest version of it.
Ben Okonkwo: And what gets trained in instead — the political class expecting rents, not revenue from citizens — that's not a habit you unlearn through a fund mandate or a diversification target. The whole coalition was built around the rent stream. Zambia's bureaucrats, Nigeria's officers, Uganda's military budget by 2016. That expectation becomes structural.
Marcus Vale: So the trap is durable not because leaders are greedy — frankly, greed is portable, you can work around greed — but because the entire system stopped needing citizens. And you can't unlearn that from the top.
Ben Okonkwo: That's where I land too. Sitting with that a bit.
Marcus Vale: Good conversation. Genuinely.